5 Checks Before Investing in Memory Care Deals
Real Estate, Senior Housing, Memory Care Investing
Five Things to Check Before Investing in a Memory Care Deal
Due diligence in a senior housing syndication can feel overwhelming, especially when a sponsor’s pitch deck looks polished and confident. One practical way to cut through the noise is to focus on five specific areas that, together, cover most of the meaningful risk in a memory care deal.
1. Financial Due Diligence: Look Beyond the Projections
Memory care investments are often sold on glossy pro formas showing attractive returns. Yet those numbers only matter if they are grounded in reality. Financial due diligence starts with reviewing actual historical financials, not just the sponsor’s forward-looking assumptions.
Ask for trailing 12-month and preferably 3-year income and expense statements for the property, including occupancy, average daily rate, and net operating income.
Compare the sponsor’s underwriting assumptions (rent growth, occupancy, expense ratios, staffing costs) to those historical numbers and to market benchmarks.
Review debt terms, reserves, and sensitivity analyses showing what happens if occupancy or rates underperform.
This matters because memory care is an operationally intensive business. Labor, regulatory compliance, and medical-related costs can move quickly. When a sponsor provides full financial statements, rent rolls, and underwriting models for your review, it signals transparency and gives you a realistic picture of potential cash flow and downside risk.
2. Licensing and Regulatory History: Confirm a Clean Record
Memory care communities operate under state-specific licenses and are subject to routine inspections. A property can look beautiful in photos yet have a troubling regulatory history behind the scenes. Your due diligence should include a review of licensing status and regulatory reports for both the property and the operator.
Verify that all required licenses are current, in good standing, and appropriate for the level of care being provided (e.g., memory care, assisted living).
Request recent state survey reports, inspection findings, and any plans of correction, ideally for several years back.
Ask whether there have been fines, license actions, substantiated complaints, or reportable incidents at the community.
This matters because regulatory problems can lead to forced occupancy reductions, reputational damage, or even license suspension, all of which directly impact revenue and property value. A sponsor who proactively shares inspection reports and explains any past issues demonstrates respect for both resident safety and investor capital.
3. Operator Track Record: Evaluate Who Runs the Day-to-Day
In memory care, the operator’s capabilities often matter more than the real estate itself. A strong building with a weak operator can quickly become a struggling asset. Your focus should be on the operator’s history and performance across their portfolio, not just the sponsor’s marketing narrative.
Review the operator’s years in business, number of communities managed, and specific experience with memory care versus general senior housing.
Ask for historical occupancy, staff turnover, and margin performance across their existing properties, as well as references from lenders or prior equity partners.
Understand their care philosophy, staffing model, training programs, and how they handle challenging resident behaviors common in memory care.
This matters because consistent occupancy, stable staffing, and positive family reviews are usually the result of an experienced operator executing a repeatable playbook. When a sponsor provides detailed operator bios, portfolio metrics, and case studies from previous properties, it gives you confidence that the business plan is grounded in proven execution, not theory.
Reviewing financials, regulatory reports, and operator history together reveals the true risk profile.
4. Physical Condition and Deferred Maintenance: Inspect the Real Asset
Memory care residents and their families are highly sensitive to environment. Outdated finishes, worn flooring, or inadequate lighting can hurt marketability, while hidden building issues can surprise investors with large capital calls. A thorough review of the property’s physical condition and deferred maintenance is essential.
Request recent property condition assessments, engineering reports, and documentation on major systems such as roofs, HVAC, elevators, fire life safety, and security.
Review capital expenditure plans and budgets, including how renovation or repositioning costs are being funded and scheduled.
Pay attention to features that directly impact resident safety and dignity, such as secure outdoor spaces, wayfinding, lighting, and bathroom design.
This matters because unexpected repairs erode returns, and a tired-looking community can struggle to compete with newer options. When a sponsor shares third-party inspection reports, detailed renovation scopes, and realistic reserve plans, you can better gauge whether the property condition supports the projected occupancy and rent growth.
5. Insurance Coverage: Protecting Against the Unexpected
Memory care communities carry unique risks related to resident health, elopement, falls, and professional liability. Adequate and well-structured insurance coverage is a critical line of defense for both residents and investors, yet it is often glossed over in offering materials.
Review property insurance, general liability, professional liability, workers’ compensation, and any specialty coverage relevant to memory care operations.
Confirm coverage limits, deductibles, exclusions, and whether there is umbrella or excess liability protection in place.
Ask whether the operator has faced prior claims and how those were resolved, as well as how premiums and coverage are projected to change over the hold period.
This matters because a single uninsured or underinsured event can wipe out years of returns. When a sponsor provides full insurance summaries, broker letters, and a clear explanation of how risk is managed, it signals a sophisticated approach to protecting both residents and investor capital.
Bringing It All Together: Documentation Builds Confidence
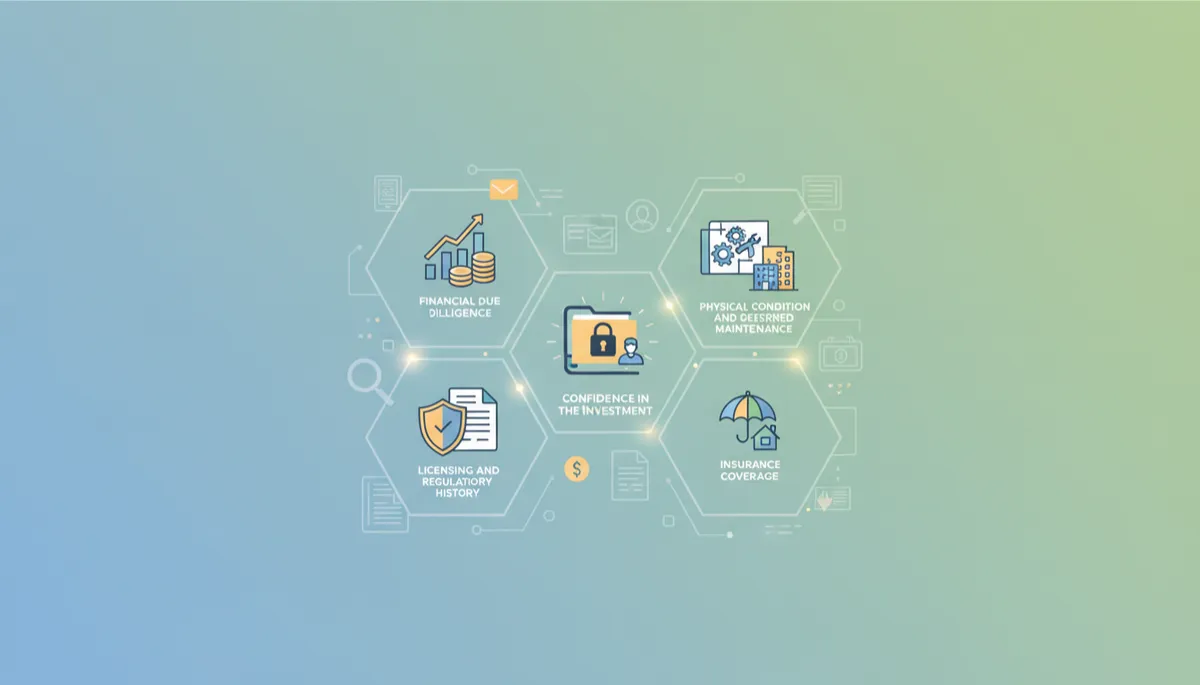
No investment is risk-free, and that is especially true in a complex, care-driven asset class like memory care. However, focusing your due diligence on these five areas—financials, licensing and regulatory history, operator track record, physical condition, and insurance—covers most of the meaningful risk in a typical memory care syndication.
The key is not just asking questions, but insisting on documentation: actual financial statements, regulatory reports, operator performance data, property condition assessments, and detailed insurance summaries. A sponsor who thoroughly addresses each of these, backs up their claims with third-party reports, and welcomes your scrutiny is far more likely to be a trustworthy steward of your capital.
When you encounter a memory care deal where these five boxes are clearly and transparently checked, you have a much stronger foundation for deciding whether the opportunity aligns with your risk tolerance and long-term investment goals.


