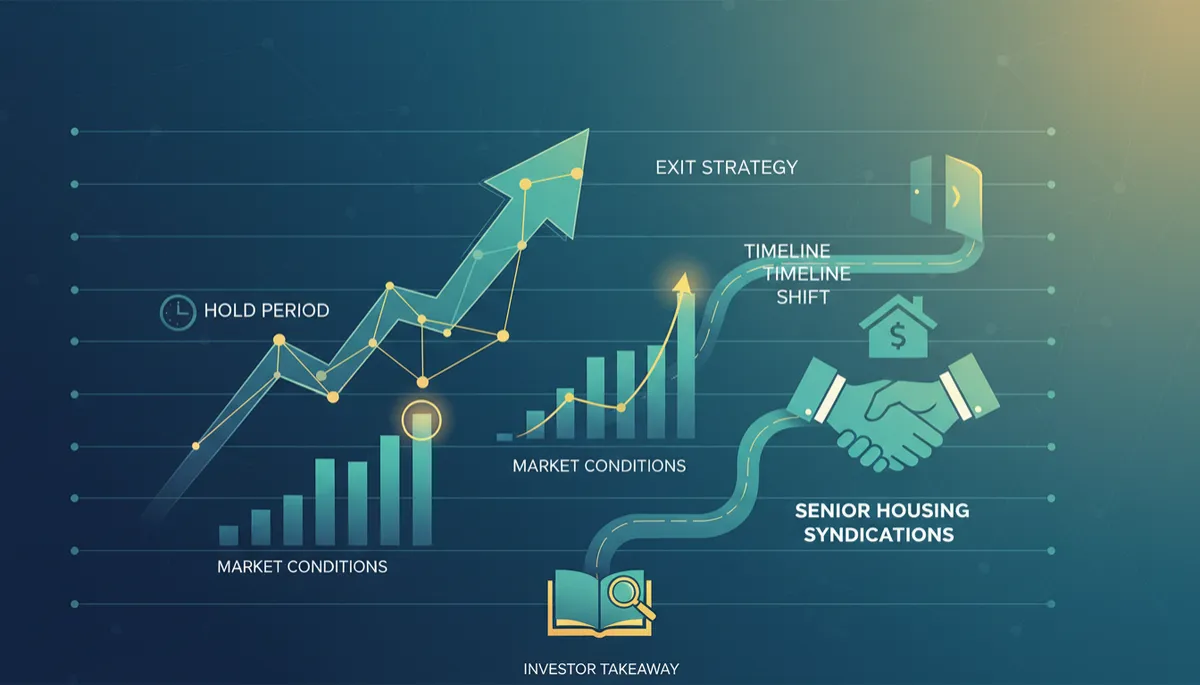
Maximize Returns: Hold Periods & Exit Strategies
Senior Housing, Real Estate Syndications, Investor Education
How Hold Periods and Exit Strategies Shape Your Return Timeline
For first-time investors exploring senior housing syndications, the projected “5–7 year hold” and “sale in year 6” can sound like background details. In reality, your hold period and the exit strategy are two of the biggest forces shaping when – and how – you actually see your returns.
What the Hold Period Actually Represents
In a senior housing syndication, the hold period is the sponsor’s best estimate of how long they plan to own and operate the property before executing the exit strategy. It is not a guaranteed maturity date like a CD. Instead, it reflects:
The time needed to complete renovations or repositioning of the community
The period required to stabilize occupancy and improve operations
The window in which the sponsor expects an attractive sale or refinance opportunity
During this time, you may receive ongoing cash flow from operations, but the bulk of your profit often comes at exit. That makes the hold period the backbone of your return timeline – when you realistically expect your original capital and appreciation to come back to you.
Why the Exit Strategy Drives the Entire Business Plan
The exit strategy is how the sponsor plans to return your capital and realize gains – usually through a sale, refinance, or recapitalization. Everything in the business plan is built backward from that intended exit:
Renovation scope and timing are chosen to maximize value by the target exit year.
Staffing, marketing, and care programs are designed to reach specific occupancy and revenue targets before exit.
Debt terms (interest-only periods, maturity dates, covenants) are selected to align with the planned sale or refinance.
If the plan is to sell to an institutional buyer in year six, for example, the sponsor is targeting a property that, by then, meets that buyer’s expectations for stabilized occupancy, strong financials, and modern amenities. Your projected returns assume that this exit can be executed roughly on schedule and at the forecast price.
Clear timelines and defined exits help investors set realistic expectations for returns.
How Market Conditions at Exit Affect Your Return
Even with excellent operations, market conditions at the time of exit have a major impact on your outcome. In senior housing, factors like interest rates, cap rates, investor appetite, and local supply and demand all influence what a buyer is willing to pay or what terms a lender will offer on a refinance.
If cap rates compress and demand is strong, the community may sell for a premium, boosting equity multiples and IRR.
If interest rates spike or buyers pull back, the property might command a lower price, or a refinance may return less capital than projected.
This is why the exit strategy is described as a plan, not a promise. A strong sponsor will underwrite conservatively, build in buffers, and be willing to adjust the timeline if market conditions are temporarily unfavorable.
What Happens If the Timeline Shifts?
In reality, many senior housing investments do not exit on the exact month originally projected. The hold period may shorten if:
The sponsor receives an unsolicited strong offer earlier than expected.
The business plan is executed ahead of schedule and market pricing is attractive.
Conversely, the hold period may extend if:
Construction or licensing takes longer than planned, delaying stabilization.
Market conditions are soft at the planned exit, and waiting may protect value.
A shift in timeline can change your internal rate of return (IRR), because IRR is highly sensitive to when cash flows are received. Extending the hold with steady cash flow may still be attractive for some investors, but problematic for others who needed liquidity on the original schedule.
📌 Key Takeaway: A flexible, well-communicated timeline is a sign of risk management, not disorganization. Ask how the sponsor decides whether to sell, hold, or refinance if conditions change.
Matching the Hold Period to Your Personal Timeline
Because senior housing syndications are generally illiquid – you cannot easily sell your shares on demand – it is crucial to match the projected hold period with your own financial plans. Ask yourself:
Can I comfortably leave this capital invested for at least the full projected hold, plus some buffer?
Do I have other sources of liquidity for emergencies or near-term goals?
Am I investing retirement funds, college savings, or capital I might need sooner?
For many first-time investors, using capital that is genuinely long-term – such as a portion of retirement funds in a self-directed IRA – can be a better fit than money earmarked for short-term goals. The more your personal timeline aligns with the sponsor’s plan, the more comfortable you will feel riding through normal market ups and downs.
Investor Takeaway: Understand the Timeline Before You Commit
As you review senior housing opportunities, do more than glance at the “5–7 year hold” line. Make it a point to understand:
What the hold period represents in terms of work to be done and value to be created.
Which exit strategy is planned, and why it fits this specific property and market.
How market conditions at exit could influence your actual returns.
What flexibility exists if the timeline needs to shift and how that will be communicated.
When you clearly understand these factors – and ensure they align with your own goals and time horizon – the hold period and exit strategy become powerful tools, not fine print. That clarity can make you a more confident, more patient, and ultimately more successful passive investor in senior housing syndications.


